
Semiconductors have become the most important strategic resource of the modern world. Without them it is impossible to produce any modern device, from control units in cars and machine tools to telecommunications systems. The technology rivalry between the United States and China has led to sweeping export bans on the most advanced lithography systems and processors, triggering a global race in which every economic superpower seeks to build its own closed production chain.
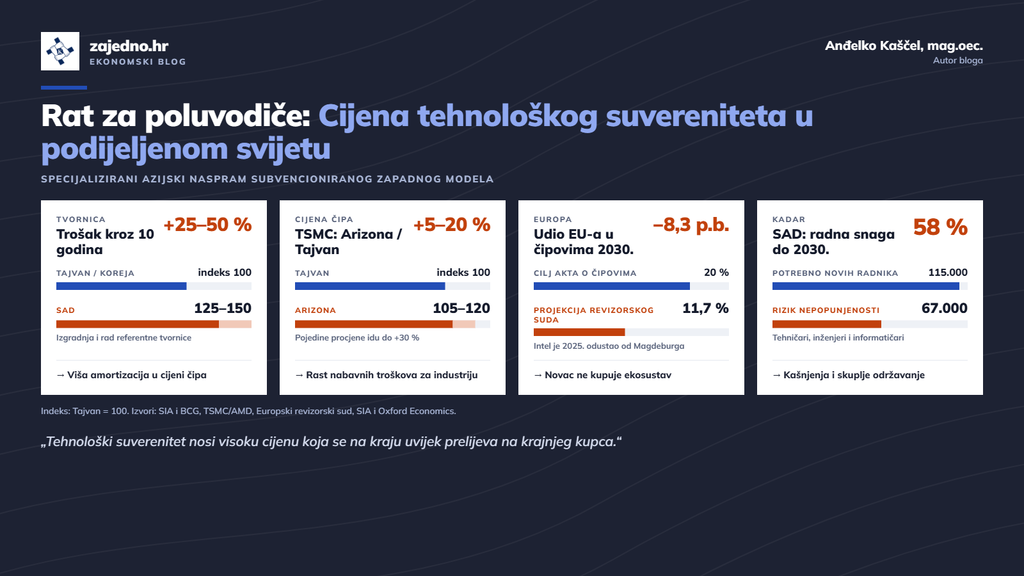
Through massive state subsidy programmes such as CHIPS Act-a Through massive state subsidy programmes such as the US CHIPS Act (52.7 billion dollars) and the European Chips Act, Western economies are trying to bring production back home. But industrial reality shows that an ecosystem built up over decades in Taiwan and South Korea cannot simply be replicated with money. The European Court of Auditors expects the EU’s share of global chip production in 2030 to reach only 11.7 percent instead of the targeted 20 percent, and Intel has abandoned its large fab in Magdeburg. New fabs in the West face delays, a shortage of highly skilled engineers and higher labour costs. The ten-year total cost of a fab in the US is 25 to 50 percent higher than in Asia, which makes chips produced in Europe and the US more expensive than Asian ones: TSMC charges 5 to 20 percent more for chips from Arizona than for those from Taiwan.
Technological sovereignty comes at a high price that is always passed on to the end customer. Instead of a globally integrated, cost-optimised market, we are entering an era of fragmented and considerably more expensive components. Manufacturers must adapt their development: modular engineering, standardised chips that can be sourced from several suppliers, and less dependence on a single technology platform are becoming essential tools of operational risk management.